

Quick answer: A diesel price swing does not change your IFTA math. IFTA tax is based on miles and gallons by state, and the price you paid per gallon is not part of the formula. What a swing does change is how drivers buy fuel: they fuel in cheaper states, buy partial tanks, use cash, or change routes. Those habits shift your state-by-state balance and create missing or mismatched records. The fix is to reconcile fuel and miles by state every few weeks, not only at the deadline.
Want a quick estimate first? Try the free IFTA calculator.
Key takeaways
- IFTA tax for each state = miles in that state ÷ your fleet MPG × that state's tax rate, minus a credit for the tax you already paid on fuel bought there.
- Pump price is not an input. A 50-cent spike raises what you spend on fuel, not what you owe on the return.
- Buying cheaper fuel in a low-tax state lowers the tax you pay at the pump but raises the balance due on your return. Plan cash for it.
- Rates are per gallon and published by IFTA, Inc. every quarter. A few states tie their rate to fuel prices or inflation, so always use the current quarter's rates.
- Returns are due on the last day of the month after the quarter ends: April 30, July 31, October 31, and January 31.
By the numbers
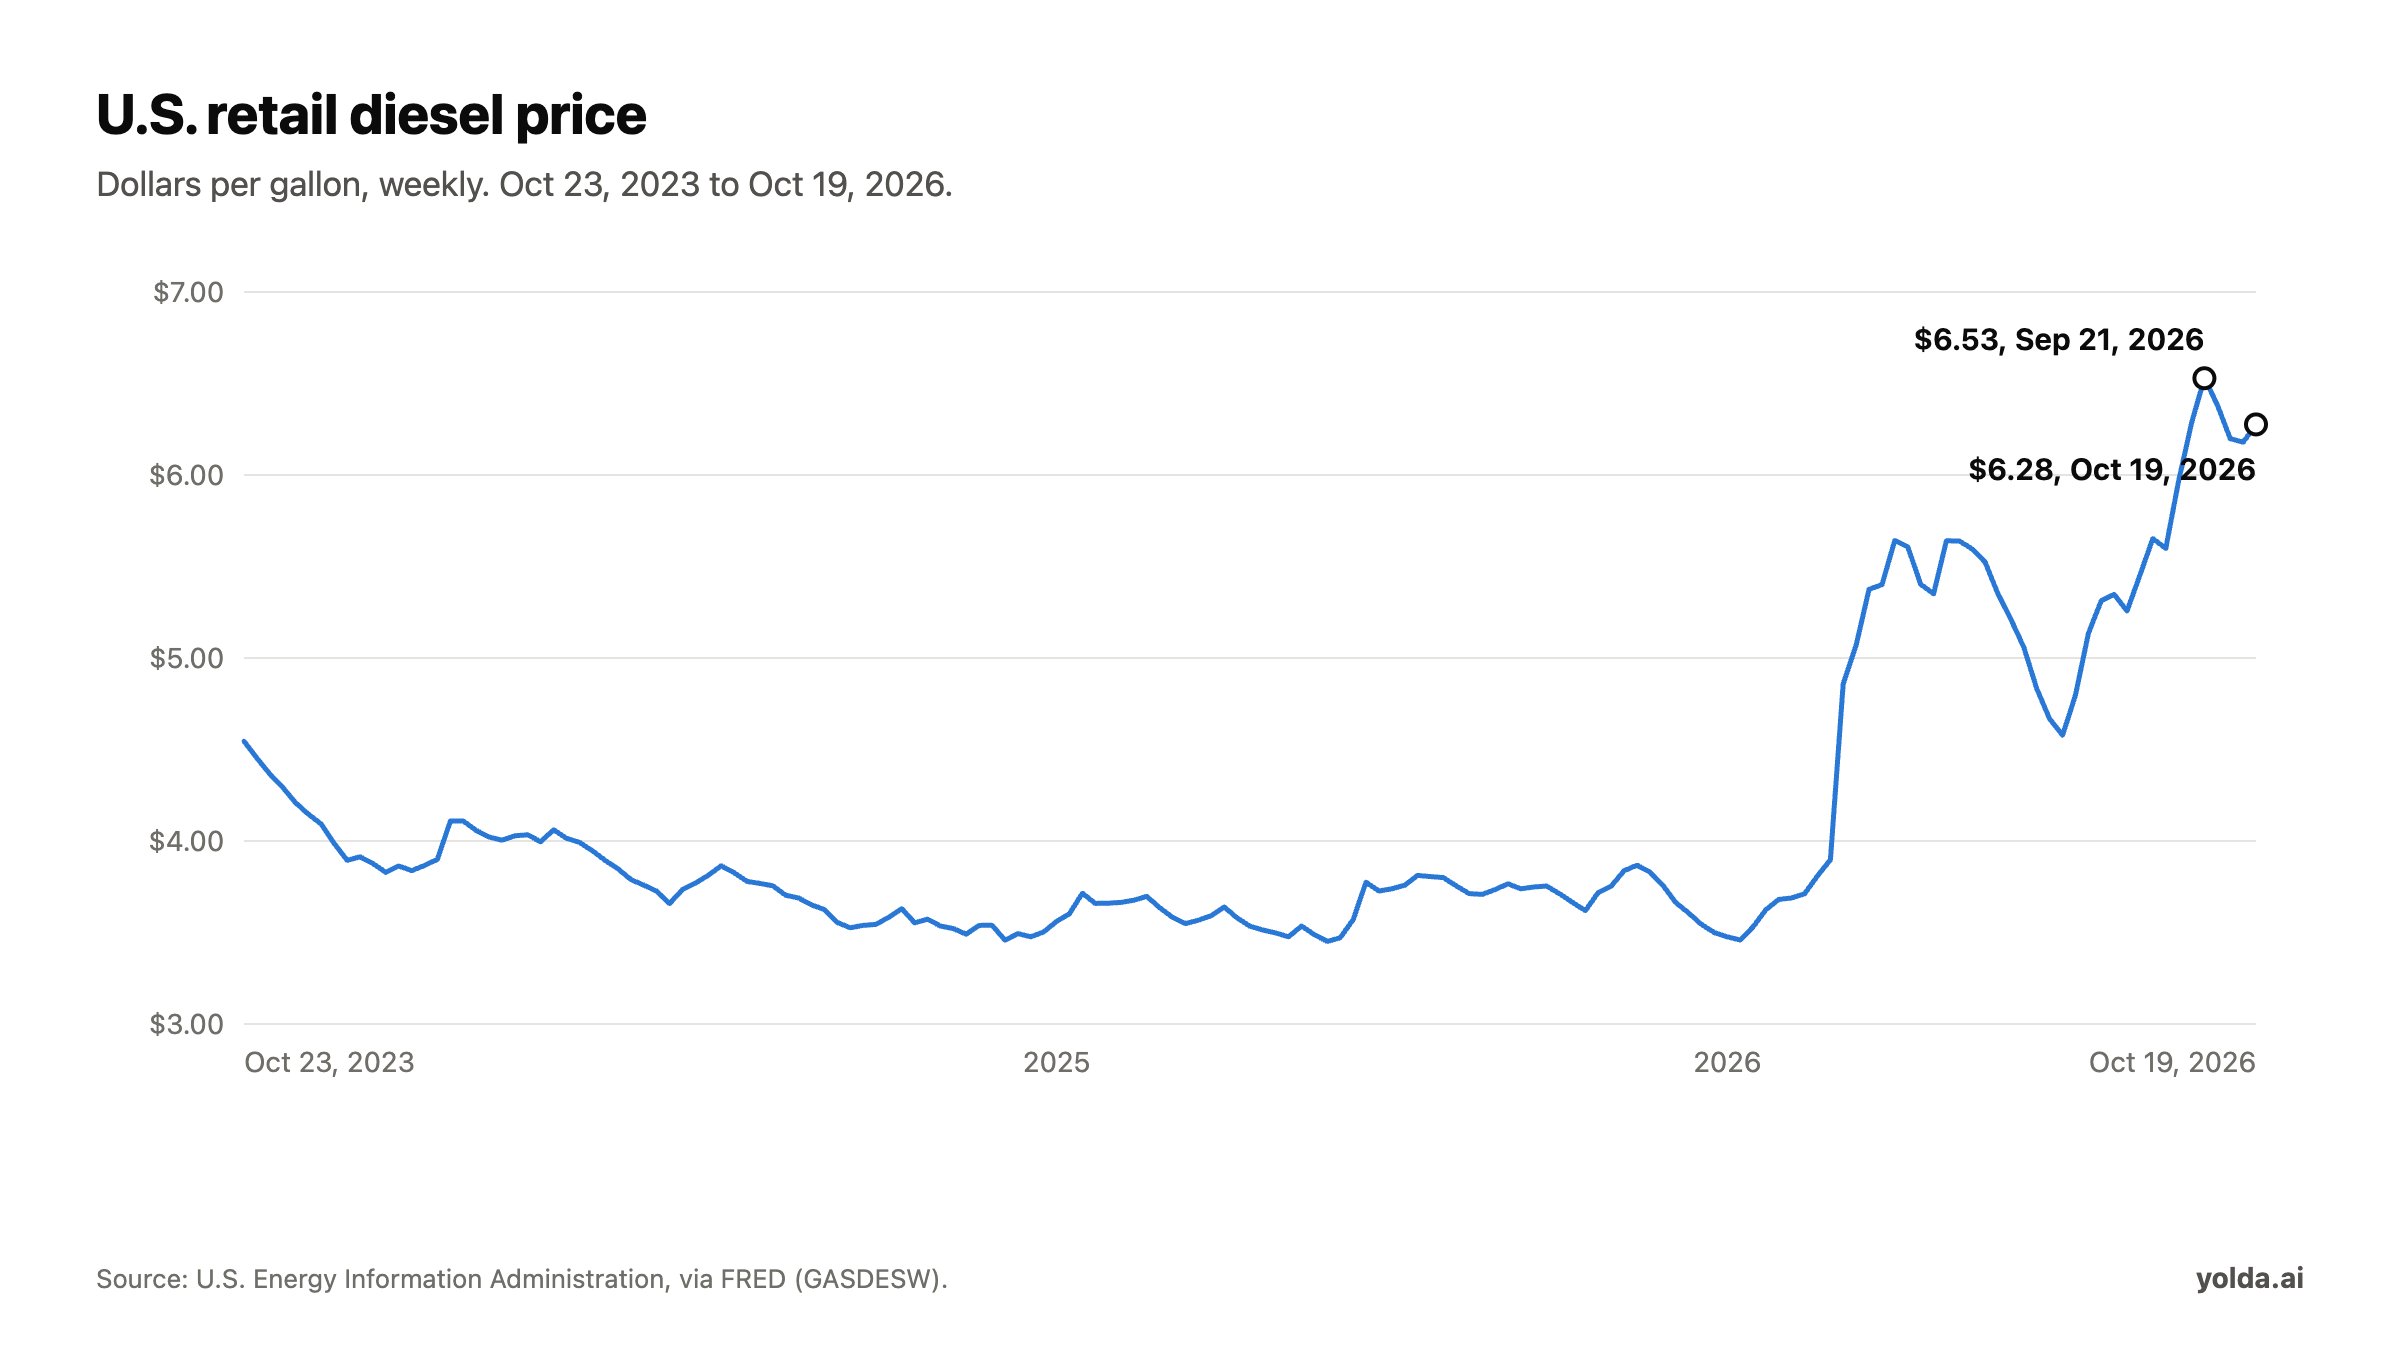
- The U.S. retail diesel price averaged $6.28 a gallon in the week of Oct 19, 2026, up $2.66 (73.4%) from a year earlier. Source: U.S. Energy Information Administration, FRED GASDESW.
Latest official data as of Oct 24, 2026.
How IFTA tax is calculated (and why price is not in it)
IFTA, the International Fuel Tax Agreement, lets a carrier file one quarterly return with its base state instead of a return in every state. The math has four steps:
- Fleet MPG = total miles in all states ÷ total gallons bought in all states.
- Taxable gallons in each state = miles in that state ÷ fleet MPG.
- Tax owed to each state = taxable gallons × that state's rate for the quarter.
- Credit = tax-paid gallons you bought in that state × that state's rate (you already paid that tax at the pump). Gallons bought without the state's tax, such as untaxed bulk fuel, earn no credit.
Tax owed minus credit is the balance for each state. A few states (Indiana, Kentucky and Virginia, for example) also charge a surcharge on the taxable gallons from step 2. It is a separate line on the return, and fuel you bought there earns no credit against it. Add the balances and any surcharges, and that is what you pay or get back. Nowhere does the price per gallon appear.
A worked example
One truck, one quarter: 30,000 miles and 4,800 gallons bought, so fleet MPG is 6.25. The rates below are made up for the example, none of the states charges a surcharge, and all fuel was bought tax-paid. Use the real rates for your quarter.
| State | Miles | Taxable gallons | Gallons bought | Example rate | Balance |
|---|---|---|---|---|---|
| A | 12,000 | 1,920 | 2,600 | $0.30 | –$204.00 (credit) |
| B | 10,000 | 1,600 | 1,200 | $0.50 | $200.00 |
| C | 8,000 | 1,280 | 1,000 | $0.40 | $112.00 |
| Total | 30,000 | 4,800 | 4,800 | $108.00 due |
Now say diesel rises 50 cents for the whole quarter. The truck spends about $2,400 more on fuel, but every number in this table stays the same. The return is still $108.
Where a price swing does move the return
Say drivers start buying 300 more gallons in State A, where fuel is cheaper, and 300 fewer in State B. The miles don't change.
| State | Gallons bought | Balance |
|---|---|---|
| A | 2,900 | –$294.00 (credit) |
| B | 900 | $350.00 |
| C | 1,000 | $112.00 |
| Total | 4,800 | $168.00 due |
The return balance went from $108 to $168. The truck paid $60 less tax at the pump in total, and owes $60 more on the return. Total fuel tax for the quarter is the same; the timing moved. If you set money aside for IFTA, plan for a bigger check when drivers chase cheap fuel.
What actually goes wrong when diesel swings
When prices jump, drivers and dispatchers change how they buy fuel. Each change is reasonable. Each one is also a chance for a record to go missing or land in the wrong state.
- Fuel bought near a state line gets coded to the wrong state.
- Partial fills and extra top-offs create more receipts, and more chances to lose one.
- Cash or personal-card purchases never reach the fuel card report.
- Bulk tank or card-lock fuel sits in a separate system and never reaches the IFTA total. A delivery into your own tank is not truck fuel until it goes into a truck.
- Route changes to avoid an expensive area are not reflected in the mileage records.
- Dates don't line up: a driver fuels at 11 p.m. and the ELD shows the state line crossed after midnight.
A missing receipt costs you the credit for those gallons. It can also make a state look at your other records. Many states treat it as a sign of a bigger recordkeeping problem.
Step 1: Keep the records IFTA asks for, as you go
Every fuel purchase needs a receipt that shows the date, the seller's name and address, the number of gallons, the fuel type, the price, the buyer's name, and the truck number. A card statement alone is often not enough. Keep the receipt.
- Capture receipts when the fuel is bought, not at quarter end.
- Match each receipt to a truck and driver, especially when trucks are swapped.
- Chase any receipt missing gallons, a location, or a date while the driver still remembers the stop.
- Keep miles from your ELD or GPS for the same dates.
- Keep records for at least four years. States can audit back that far.
Step 2: Reconcile every two to three weeks
You file once a quarter, but you don't have to wait that long to check. When prices are moving, check more often.
| How often you check | Risk when diesel is moving | Good for |
|---|---|---|
| Once a quarter | High. Gaps show up too late to fix easily | Small fleets on steady routes |
| Monthly | Medium. Catches most wrong-state errors | Most regional fleets |
| Every 1–3 weeks | Low. Errors found within days | Fleets crossing many state lines |
Each check, compare these numbers side by side:
| Check | What it catches |
|---|---|
| Gallons on receipts vs. gallons in your IFTA records | Missing or double-counted receipts |
| ELD miles by state vs. miles in your IFTA records | Route and trip logging errors |
| Fleet MPG this quarter vs. past quarters | Bad data. A jump from 6.2 to 7.1 MPG with no equipment change is almost always a mistake |
| Gallons bought in a state vs. miles driven there | Fuel bought in one state and burned in another, common near borders |
| Bulk tank and card-lock withdrawals | Fuel that never reached the total |
Step 3: Keep cash and tax separate
A swing changes how much cash you spend on fuel. It does not change how much tax you owe, except through where fuel is bought (see the example above).
Example: a 10-truck fleet, each truck running 24,000 miles a quarter at 6.5 MPG, buys about 3,692 gallons per truck. A 20-cent rise is about $738 more per truck in fuel spending for the quarter. That is a cash question, not a tax question.
| What happened | What it means | What to do |
|---|---|---|
| Diesel went up mid-quarter | Fuel spending is up; tax is not | Plan cash for fuel. Watch for drivers fueling in low-tax states, which raises the return balance |
| Diesel went down mid-quarter | Fuel spending is down; tax is not | Don't plan on a refund unless miles or fueling states changed |
To estimate the bill before the deadline, see How to Forecast Your Quarterly IFTA Bill Before It's Due.
Step 4: Use one fuel record for IFTA and driver pay
The same receipt often feeds two jobs: the IFTA return (gallons by state) and the driver's weekly statement (a fuel charge or reimbursement). If those live in two spreadsheets, someone fixes one and forgets the other, and the numbers drift apart by quarter end.
Record each fuel purchase once and let both jobs read it. Then a correction made for the statement also corrects the IFTA quarter. For the pay side of a diesel swing, see Driver Pay and Settlements When Diesel Prices Swing.
Step 5: File on time, and know when to amend
IFTA returns are due on the last day of the month after the quarter: April 30, July 31, October 31, and January 31. A late return can bring penalties and interest under the agreement, so check your base state's notice if you are close to the date.
Correct a filed return when its gallons, miles, or tax rates were wrong. Follow your base state's correction process, which may require an amended return or a separate refund form. Examples of record errors include:
- fuel was recorded in the wrong state
- miles for a state did not match the trip records
- a trip or receipt was left out
A change in fuel prices alone is never a reason to amend.
Mid-quarter checklist
- Pull fuel card totals, receipts, and ELD miles by state every two to three weeks.
- Compare gallons bought with the gallons your fleet MPG and miles predict.
- Look for trucks with an unusual MPG or a repeated fuel-vs-miles gap.
- Include bulk tank, card-lock, and cash purchases.
- Check fuel bought near state lines for the right state.
- Confirm the current quarter's tax rates before you file.
- Set money aside for a bigger balance if drivers are fueling in low-tax states.
- Record each fuel purchase once, for both IFTA and driver pay.
- Set a reminder a week before the due date.
Common questions
Does a diesel price spike raise my IFTA tax? No. IFTA tax follows gallons and miles by state. You spend more on fuel, but the return only changes if your miles, your MPG, or the states where you buy fuel change.
Do IFTA tax rates change with fuel prices? Most states charge a set amount per gallon. Some adjust their rate on a schedule, and a few tie it to fuel prices. IFTA, Inc. publishes every member's rates each quarter.
Is the tax-paid credit based on the price I paid? No. The credit is the gallons you bought in a state times that state's rate, whatever the pump price was.
Should I file early when prices are moving? File on the normal schedule, but check your records every few weeks so the data is clean when you file.
Let the worksheet build itself from records you already keep
In Yolda's IFTA module, every fuel purchase you record, from a connected fuel card, an imported card statement, or a driver's receipt photo, lands on its truck once, and its gallons flow into the quarter. Miles come from your trips and connected ELD. Yolda builds the quarterly worksheet with the official rates for that quarter and keeps it with its sources. It is a calculation you review; you or your preparer still file the return with your base state.

